Debt management is a crucial part of personal finance. The key to successful debt management is simple: don’t spend more than you earn. However, not all debt is created equal. There are different types of debt, each with its pros and cons.

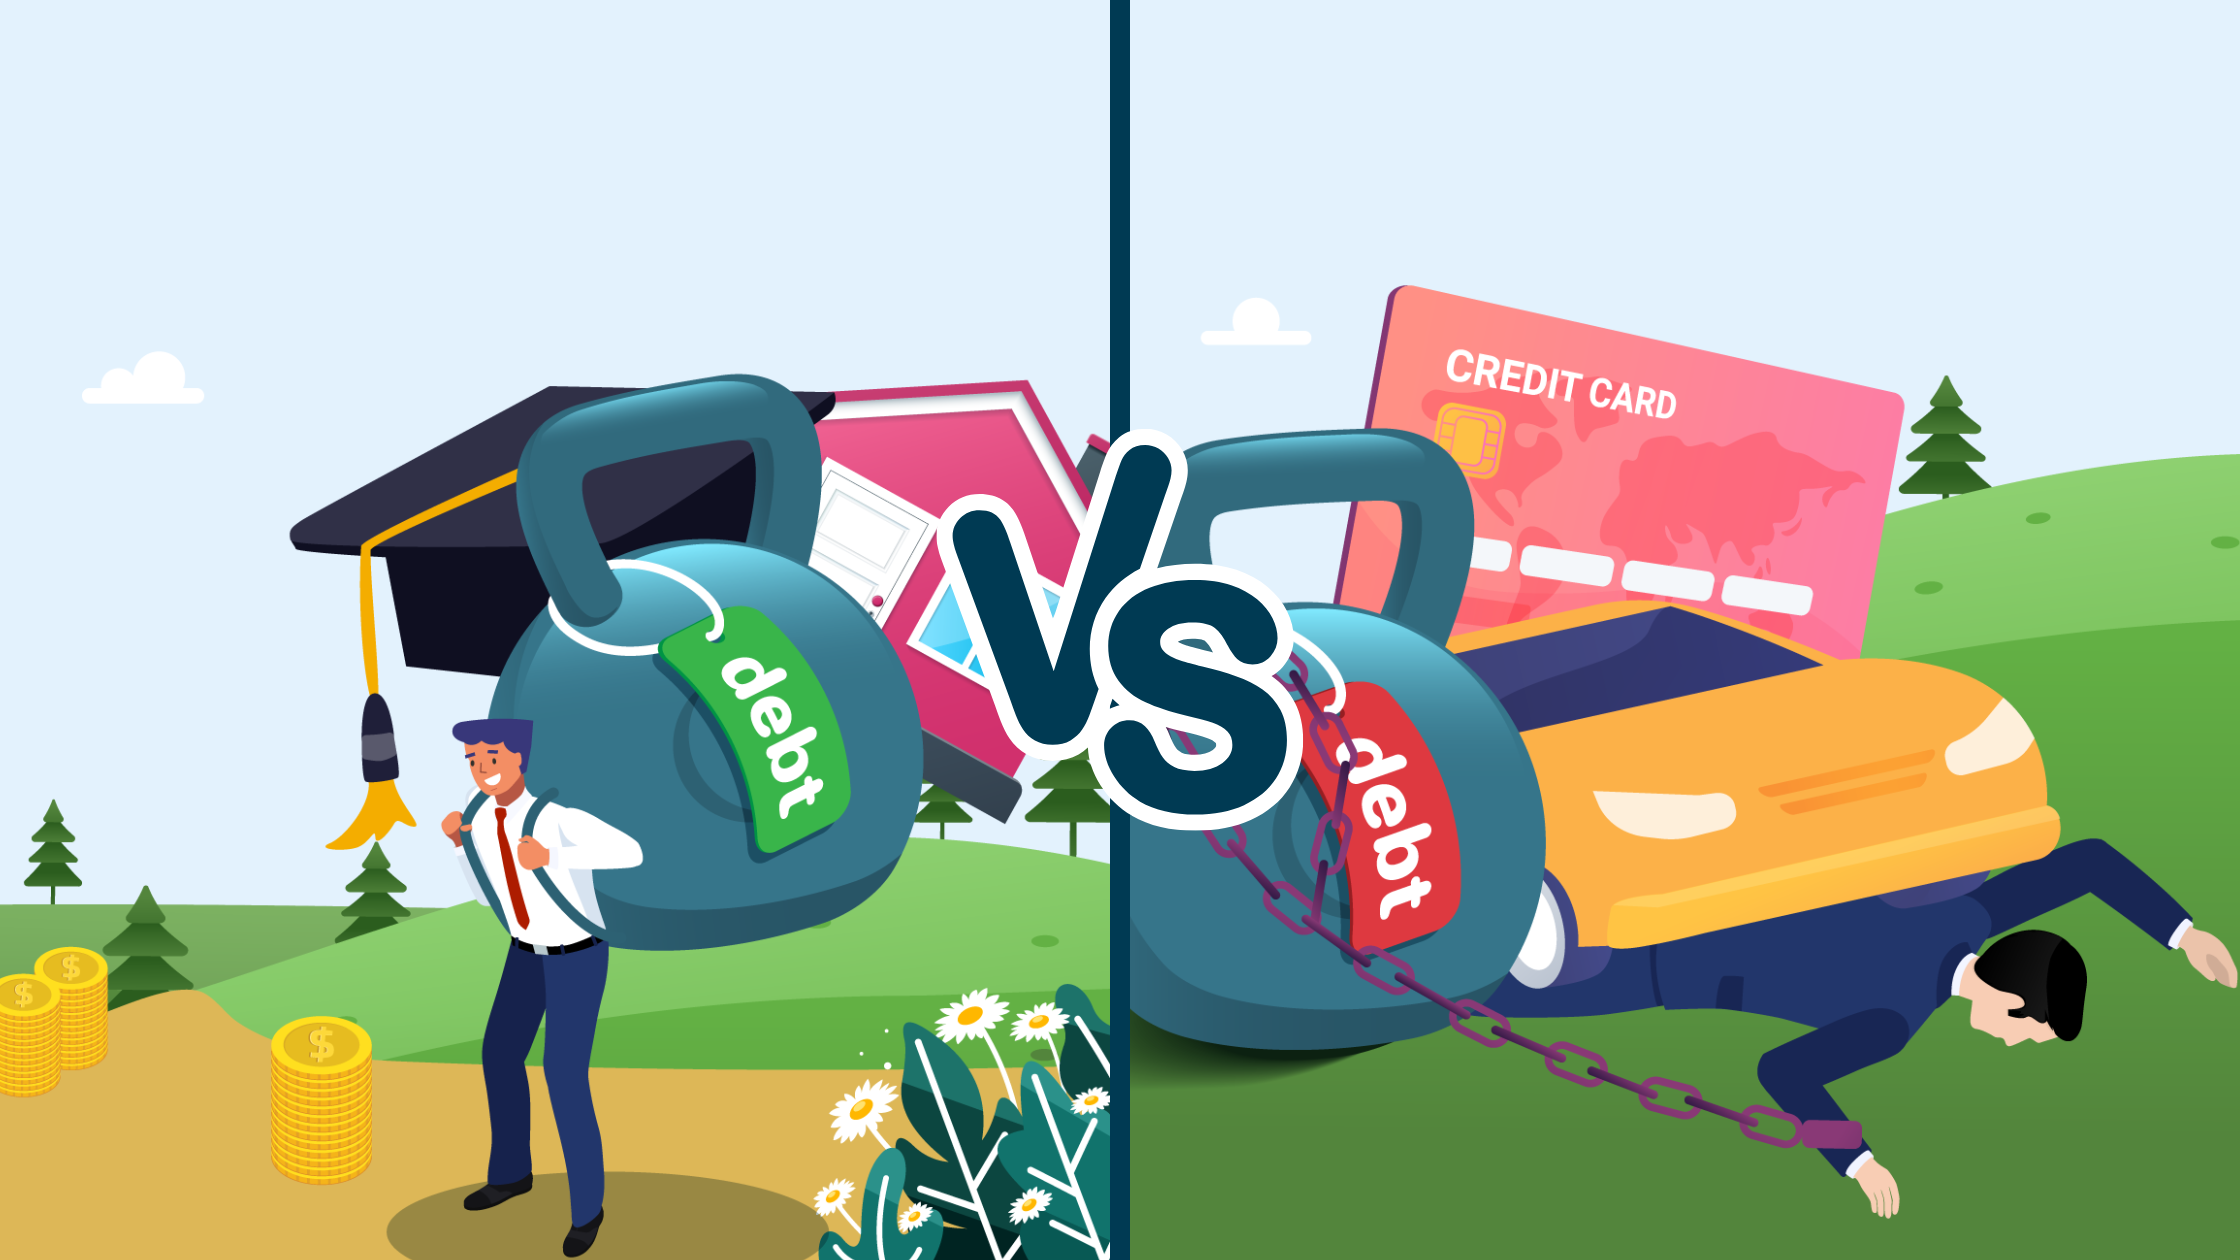
Good debt is usually a debt that is necessary to generate income or build your net worth, such as student loans and mortgages. These debts help you increase your earning capacity and asset accumulation. Good debt typically has interest rates of 1% to 4%. Instead of paying full university fees and a house upfront, the freed-up cash flow can be invested elsewhere with a higher return rate.

Bad debt, on the other hand, is usually a debt that is used to buy something that decreases in value. For example, car loans. New cars lose around 10-30% of their value once driven out of the showroom. It’s better to save up to buy a used car where the majority of its depreciation has already occurred or to pay a bigger down payment for it. 

Neutral debt includes buy now, pay later (BNPL), 0% instalment plans, and credit cards. These loans are becoming increasingly popular in Malaysia. If used responsibly, they can free up your cash flow and help you save with cashback. However, if you spend beyond your means and only make the minimum payments, you could rack up huge amounts of debt with an interest rate of up to 20%. 

Once you have a handle on the different types of debt and how to manage them, you can start focusing on investing. Investing is a way to grow your wealth by putting your money into assets that have the potential to earn a return. By having a long-term perspective and diversifying your portfolio, you can set yourself up for financial success and achieve your goals.

Have any questions?

Ask here!
Find your milestone number

Your milestone

Emergency fund

A common rule of thumb is to keep 6 months of expenses set aside. Tell us what you spend in a month and we'll work it out.

First home

Most Versa users planning to buy are looking at homes between RM300,000 and RM500,000. A 10% down payment is typical, and you'll also need to budget for legal fees and other costs.

Wedding

Weddings in Malaysia typically cost around RM40,000 to RM60,000. Adjust it to the day you have in mind.

Child’s education

University costs vary a lot depending on the course and whether it's local or overseas. Start with an estimate and adjust it.

Dream trip

Pick your destination and set a budget. Smaller goals are a great way to build the habit.

Retirement

Set the amount you’d like to have for the years after work. Long timelines are where investing and PRS can help most, and PRS also gives you up to RM3,000 in tax relief a year.

Your own milestone

Whatever you're working towards, set a target and a timeline and we'll show you the monthly amount it takes.

Your next moveRM–RM0a month*

to reach your emergency fundfirst homeweddingchild’s educationdream tripretirementgoal in year.years.

Fill in your target and timeline to see your number.

You’re already there. Time to set your next milestone.

Goal
Saved
To go

% of the way there

*For illustration purposes only

Get a kickstart towards your emergency fundfirst homeweddingchild’s educationdream tripretirementgoal: download the Versa app and enter this code when you sign up.

Cash in a min. of RM100 into any Versa product and get a RM5* head start towards your goal. *T&Cs apply.

For illustration purposes only. Private Retirement Scheme (PRS) savings can generally only be withdrawn from age 55, except in limited cases allowed under PRS rules.