
Let’s be honest – retirement can feel far away, kan? But with everything getting pricier (hello, inflation!), starting early can be a big win. And here’s a smart way to do it: the Private Retirement Scheme (PRS). Not only does PRS help you save for your future, but it also offers some sweet tax relief along the way – win-win, right?
What’s PRS, Anyway?
PRS (Private Retirement Scheme) is a voluntary retirement savings plan that complements your Employees Provident Fund (EPF). If you’re already saving through EPF, PRS gives you an extra way to grow your retirement fund and secure a more comfortable future. It’s like having a backup savings plan but with more flexibility and options!
You can choose from a variety of funds based on how comfortable you are with risk, your financial goals, and how long you want to save. Whether you’re looking for safer options or more growth-focused choices, PRS gives you the freedom to decide where your money goes.
Tax Relief: Why It Matters
Did you know that you can save even more by investing in Private Retirement Scheme? All Malaysians earning an annual income of more than RM34,000 are obligated to file and pay taxes (if applicable).

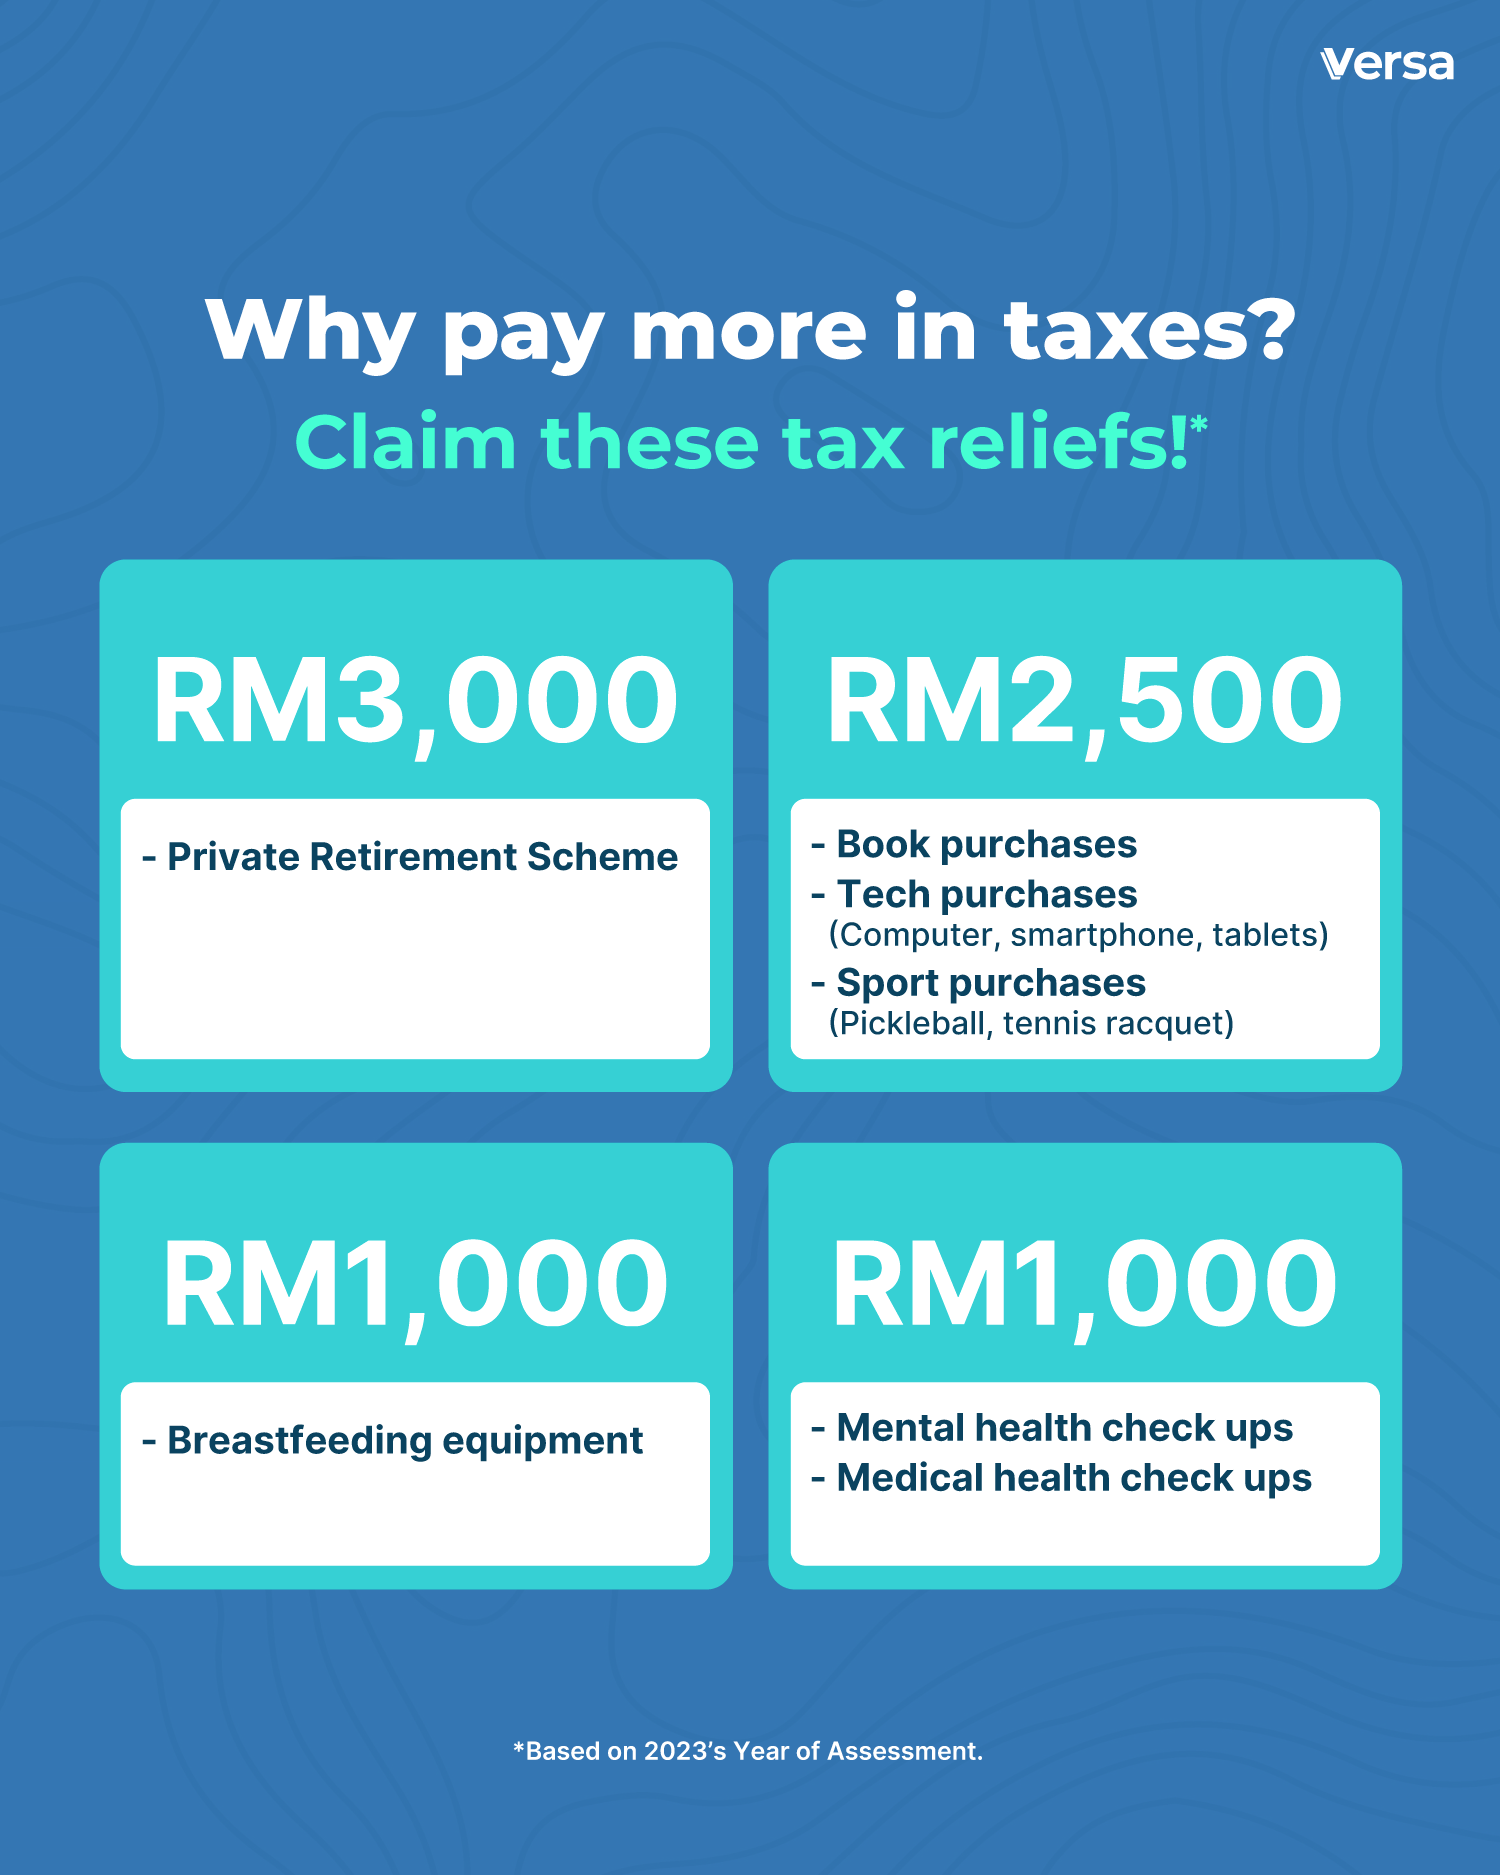
But here’s the kicker: you can use tax reliefs to reduce how much you owe the government. One of those tax reliefs is for your PRS contributions. Claim up to RM3,000 in tax relief for your PRS contributions, which means that the money you contribute can be deducted from your taxable income. This will lower your chargeable income, reducing the amount of taxes you need to pay, and could even result in a tax refund! 🎉
To make things even easier for you, we’ve put together a handy visual guide on all the tax reliefs you can claim, including those for PRS. This will help you figure out how much you can claim in tax relief for your PRS contributions and make sure you’re maximising your tax savings.
So, while contributing to PRS is helping you secure your retirement, it’s also lightening your current tax load – two birds, one stone.
How PRS Complements Your EPF
EPF is mandatory, and while it’s a great foundation for retirement, it may not be enough for all of us to retire comfortably. That’s why PRS is such a valuable addition. PRS lets you boost your savings in a more flexible way, with the potential for higher returns, depending on the funds you choose.
The CEO of Private Pension Administrator Malaysia (PPA) has mentioned that savings in EPF alone are often not sufficient for many Malaysians. So, think of PRS as that extra cushion to help you live out your retirement dreams without worrying about money.
Choose Your PRS Adventure: Safe or Bold?
One of the best things about PRS is that you have the flexibility to choose the right fund for you. Whether you want to play it safe or take on a bit more risk, there’s a fund for everyone.
• Conservative Funds: If you’re risk-averse and prefer more stable returns, these are for you. Safe and steady wins the race.
• Balanced Funds: For those who want a mix of security and growth. Perfect if you’re not afraid of taking a calculated risk.
• Growth Funds: If you’re ready to go big and potentially earn higher returns (with higher risk), growth funds will suit you.
The choice is yours – you can even mix and match based on your goals.
Bonus Time: Get RM100* for PRS via Versa! 🎁
Now, let’s make this even sweeter. At Versa, we’re offering an RM100* Versa Save bonus when you invest in PRS through us. Not only are you securing your future with PRS, but you’re also getting a little something extra just for signing up. So why not? It’s a no-brainer!
➡ Read Stack and Earn: 3K PRS Quest
How to Get Started with PRS – It’s Easy!
1. Sign up on Versa (it only takes a few minutes!) OR log in if you’re an existing user!
2. Go to Versa Retirement.
3. Pick a fund that fits your risk appetite.
4. Start contributing – and claim your tax relief!
The process is simple, and you’ll be well on your way to building a stronger financial future.
The Bottom Line: Why PRS is a Must
So, why wait? If you’re not already contributing to PRS, now’s the time to start. With tax relief and the ability to grow your retirement savings, it’s one of the smartest moves you can make. Plus, you’re not just saving for tomorrow – you’re saving on taxes today. So, don’t miss out on this opportunity!
Happy PRS-ing! 🎉
*T&Cs apply. Please refer to the respective Quest’s terms and conditions here.