You have probably been told repeatedly the importance of saving money. Often it starts at home with your parents teaching you the how’s and why’s you need to save money. However, as adult life hits there is just so much going on that people forget why they need to save, in favor of ‘all the things they need’.
That mentality does not negate the fact that sometimes, you need to have cash on hand in a pinch.
How much cash should you have on hand?
Not to be confused with emergency funds, your cash on hand serves the purpose of something like a rainy-day fund. For example, if you lose your job, or there is a recession, better yet, a global pandemic.
If Covid-19 has taught the world anything, it’s that you should build your financial cushions while you still have the chance.
To determine the amount of cash you need to have on hand per month, simply add up all your monthly expenses + 20% more like a cushion. Include first your fixed expenses, home loans, rent, student loan, hire purchase (car loan), electricity, petrol, water, food, and subscriptions. Now add 20% more to that number and you have a rough estimate of how much you’ll need a month.
Example: Person A
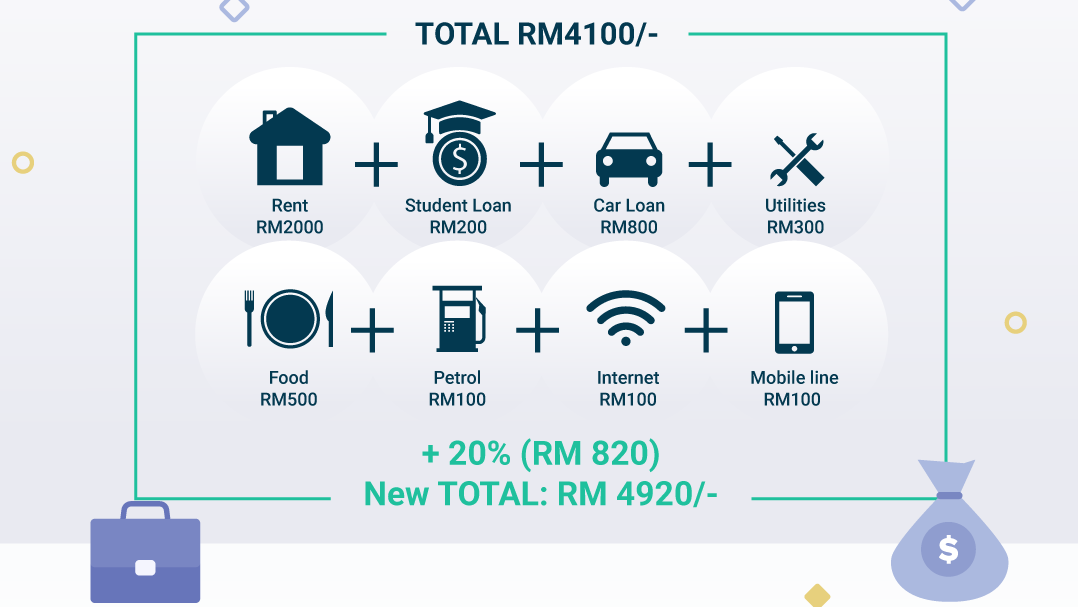
With the 20% added as a cushion, Person A will need to have RM 4920 inaccessible cash for a rainy-day month. Then again, rainy days don’t happen just once. The Movement Control Order here in Malaysia is still ongoing, which means anything can happen, and if you have been laid off, sometimes it takes a few months to secure a new job. To circumvent surprises, you would need to triple that savings estimate to hold you over for at least 3 months. In which case Person A, would need to have a total of RM 4920×3 = RM 14,760. Let’s make that a whole number and say RM 15k.
Did you notice how there is no mention of Credit Cards? Well, here’s some friendly advice, credit cards are for emergencies, gaining debt on a credit card makes the savings process harder. You’ll end up having to allocate more for card payments, so if you have not already started using one, don’t. If you have, well you might need to increase your cushion to double the amount, bring your three-month bucket to RM 30,000.
Where to save this money?
Typically, this savings would be in a secondary savings account for both accessibilities and to earn some interest. You could probably expect though, that for the amount you need to be saved, that value will not earn you an extremely high return, with savings accounts only having an average interest of maybe 0.3% p.a.
Long-term fixed deposits and investment plans are also out of the question, as fees are incurred if you need to make a hasty withdrawal. You could, of course, opt for a short-term fixed deposit maybe 3-6 months to grow that income in small doses. However, the risk remains if you need it, your funds are locked in and you might find yourself cashless.
Luckily, there is another option.
Money Market Funds (MMF) are stable high-income and low-risk investment details that offer you both great returns and the liquidity you need. MMFs are one of the financial world’s best-kept secrets, no one knows about them because they are only used by large corporations or businesses. Let it be known though, there are personal finance options for MMFs.
New to the market is Versa. Versa is a digital cash management platform that can help you better manage your cash with both low risk and returns of up to 10x higher than any savings account. It is a Money Market Fund dream come true. You can be sure that your money is both safe and stable but with full liquidity. No commitments, no hidden fees, and no lock-ins. Turn your cushion into a cash cow and when you do need that money for a rainy day, you need to look no further.